Quick Answer: Property data collection is an on-site visit by a trained, vetted data collector who records interior and exterior facts, photos and a floor plan, without giving an opinion of value. Fannie Mae uses it in value acceptance + property data, and Freddie Mac uses it in ACE+ PDR, so some eligible loans can close without a traditional appraisal. When a loan is not eligible, or the lender decides it wants one, an appraisal is still required, and that is where an AMC such as R3 AMC comes in. Call (702) 658-1191 to place appraisal orders.
Fannie Mae and Freddie Mac have spent several years building ways to confirm collateral without a full appraisal on every loan. The newest tools pair automated valuation analytics with a property visit by someone who collects data but does not value the home. For lenders, that means fewer appraisals on some files and new questions on others. This article explains what property data collection is, how the two agency programs work, and when an appraisal is still the right call.
What Is Property Data Collection?
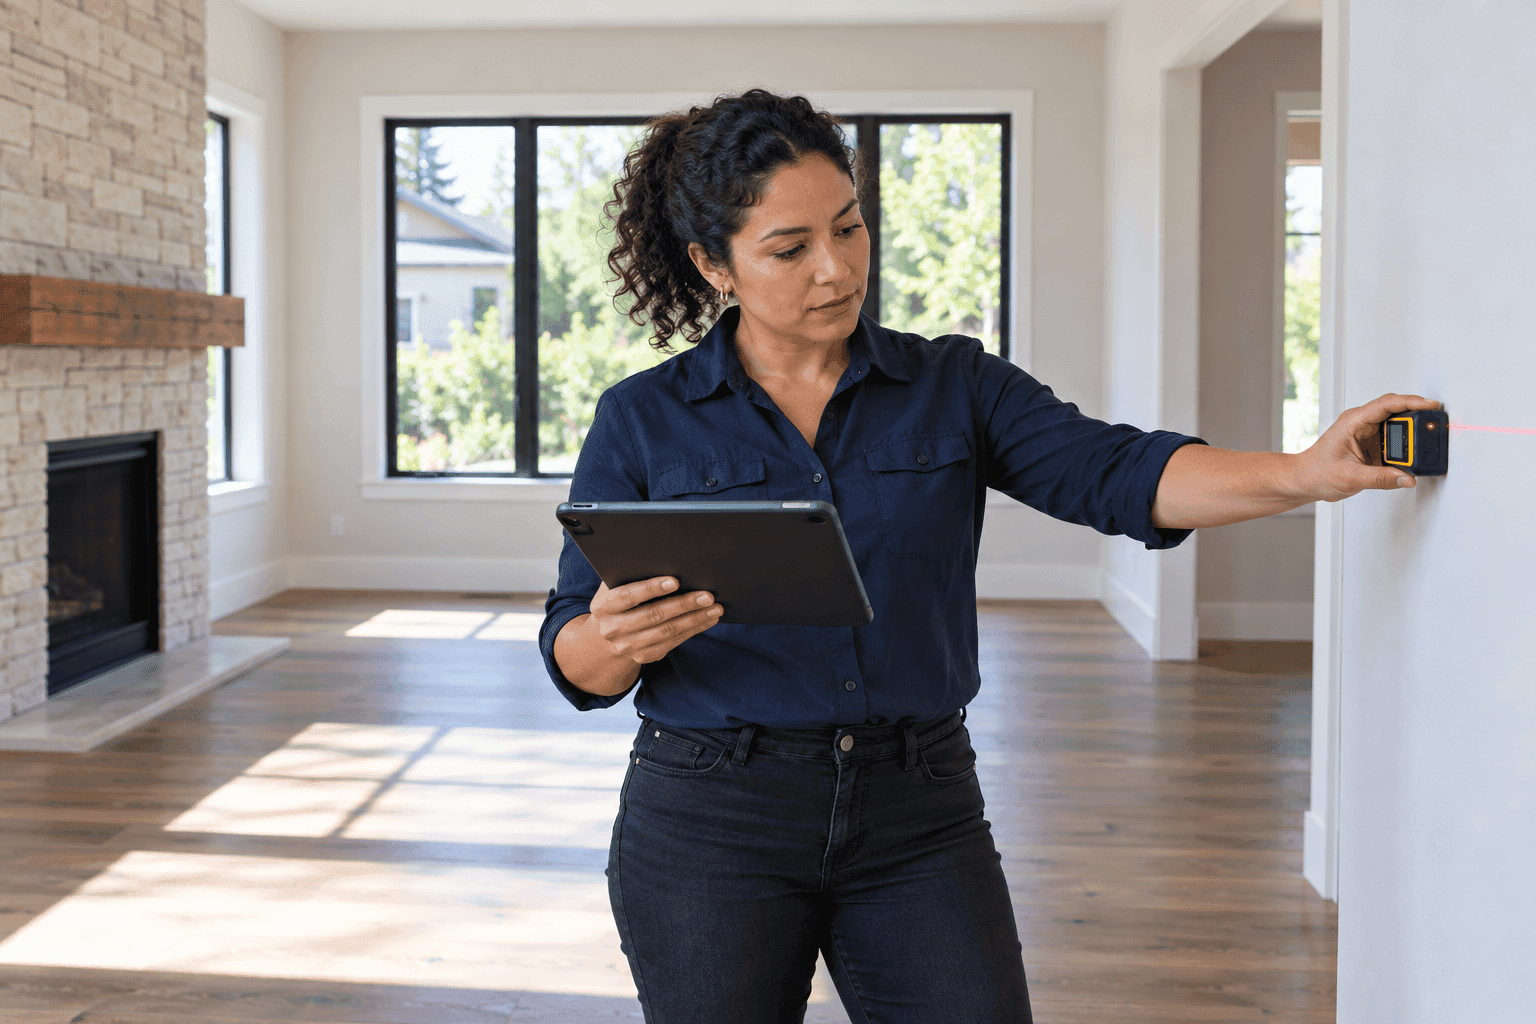
Property data collection is a structured on-site inspection that captures facts about a home. Fannie Mae describes the collector as a trained and vetted property data collector. That person does not have to be an appraiser. The lender must confirm that each collector has an annual background check, professional training and an annual review of credentials, and the collector cannot have any interest in the loan, its parties or the property.
The visit covers both the interior and the exterior. During the visit, the collector takes photos, measures the home, produces a floor plan to the ANSI measurement standard and reports any safety, soundness or structural issues. All of the data follows the Uniform Property Dataset (UPD), a common format that Fannie Mae and Freddie Mac built together. The key point for lenders is that a data collection is a set of facts. It is not an opinion of value.
How Does Fannie Mae Value Acceptance + Property Data Work?
Value acceptance is Fannie Mae's offer, made through Desktop Underwriter (DU), to accept the lender's value without an appraisal. Many lenders still know it by its older name, appraisal waiver. Our article on property inspection waivers covers that offer in more detail.
Value acceptance + property data adds the on-site data collection to Fannie Mae's analytics. Key rules from Selling Guide section B4-1.4-11 and Fannie Mae's program page include:
- The DU offer must be no more than four months old on the note date.
- The property data collection is valid for 12 months from the date it is collected.
- The data must be submitted to Fannie Mae's Property Data API before the note date.
- Eligible properties are one-unit homes, including condo units, valued under $1,000,000.
- Two-to-four unit homes, co-ops, manufactured homes, construction loans and HomeStyle loans are not eligible.
How Does Freddie Mac ACE+ PDR Work?
ACE+ PDR (Property Data Report) is Freddie Mac's version. Freddie describes it as a collateral valuation offering that lets lenders deliver eligible loans without an appraisal report. The lender first submits the loan to Loan Product Advisor (LPA), which must return an Accept. If the loan is offered ACE+ PDR, a data collector visits the home and submits the data through Freddie Mac's API, using the same UPD format.
According to Freddie Mac's program fact sheet, ACE+ PDR can apply to purchases and both cash-out and no cash-out refinances, on primary residences and second homes. Eligible properties are one-unit homes, including PUDs and condo units. Manufactured homes, co-ops and leaseholds are excluded. The data collector may be a non-appraiser, an appraiser or an appraiser trainee. Loan-to-value limits apply, so check the current Freddie Mac Guide before relying on the offer.
What Are PDC Fulfillment Providers?
Lenders rarely send their own staff to collect data. Instead, they use vendors that train and manage data collectors. Fannie Mae publishes a list of property data collection fulfillment providers on its website, and on October 8, 2026 it showed more than 70 vendors. Freddie Mac publishes its own list of more than 100 verified ACE+ PDR providers and states that it does not endorse them. Under Fannie Mae's rules, the lender selects the data collector and remains responsible for checking its quality control.
When Does a Loan Still Need an Appraisal?
Plenty of loans still need a full appraisal. Common reasons include:
- The loan or property is not eligible for value acceptance or ACE+ PDR.
- The law requires an appraisal for that transaction.
- Rental income from the property is used to qualify the borrower.
- The lender decides an appraisal is warranted, which Fannie Mae allows even when an offer is made.
- An appraisal for the property was uploaded by any lender in the prior 120 days, in which case DU will not offer value acceptance.
There is also a middle path. If a loan loses its value acceptance + property data offer, Fannie Mae says it may be possible in some cases to give the collected data to an appraiser for a hybrid appraisal, where the appraiser analyzes the data and signs the value opinion without visiting the home.
Where Does an AMC Fit When Fewer Loans Need an Appraisal?
The loans that still need appraisals are often the harder ones: higher-value homes, multi-unit properties, investment properties and files with a story behind them. Those are the files where appraiser selection, quality control and clear communication matter most.
R3 AMC places those harder residential files across the country for every loan type except VA. It reports more than 500 active appraisers, an average five-business-day turnaround and a review process that combines ValueTest.ai research with human review before delivery. It was also a preferred beta tester for UAD 3.6, the redesigned appraisal dataset that becomes mandatory for new GSE appraisal submissions on November 2, 2026, with a temporary exception for lenders that are not ready.
Frequently Asked Questions
Is property data collection the same as an appraisal?
No. A property data collection records facts, photos and a floor plan, but it does not include an opinion of value. The value comes from the lender's figure and the agency's analytics, or from an appraiser in a hybrid appraisal.
Does the property data collector have to be an appraiser?
No. Fannie Mae requires a trained and vetted data collector with an annual background check and professional training. Freddie Mac allows non-appraisers, appraisers and appraiser trainees to collect data for ACE+ PDR.
How long is property data valid for Fannie Mae?
A property data collection is valid for 12 months from the date it is collected. The DU offer itself must be no more than four months old on the note date.
Can a lender turn down value acceptance and order an appraisal?
Yes. Fannie Mae leaves the choice to the lender, and the lender must order an appraisal when the law requires one, when rental income is used, or when it believes one is warranted.
Does R3 AMC handle appraisals for loans that are not eligible?
Yes. Loans outside these offers are standard work for R3 AMC, which handles conventional, FHA, jumbo, non-QM, USDA and portfolio appraisals. Call (702) 658-1191 or email orders@r3amc.com to place an order.
Need an appraisal partner? Call R3 AMC at (702) 658-1191 or contact the R3 AMC team.
Key Takeaways
- Property data collection is an on-site visit that records facts, photos and a floor plan, but not a value.
- Fannie Mae uses it in value acceptance + property data, and Freddie Mac uses it in ACE+ PDR.
- Fannie Mae property data is valid for 12 months, and the DU offer must be no more than four months old at closing.
- Ineligible loans, rental income files and lender choice still lead to full appraisals.
- In some cases, data from a lost offer can support a hybrid appraisal instead of a new inspection.
- R3 AMC manages the residential appraisals these programs do not cover. Contact R3 AMC to place an order.